
Buying a home in DC, Maryland and Virginia.
The buyer agreement, the contract, contingencies, review periods, settlement and taxes, from preapproval to the keys.
Buying in the Washington region means three sets of rules. DC, Maryland and Virginia each have their own contract forms, disclosure laws, review periods and taxes. Choose where you are buying, and every rule and figure that differs shows that jurisdiction.
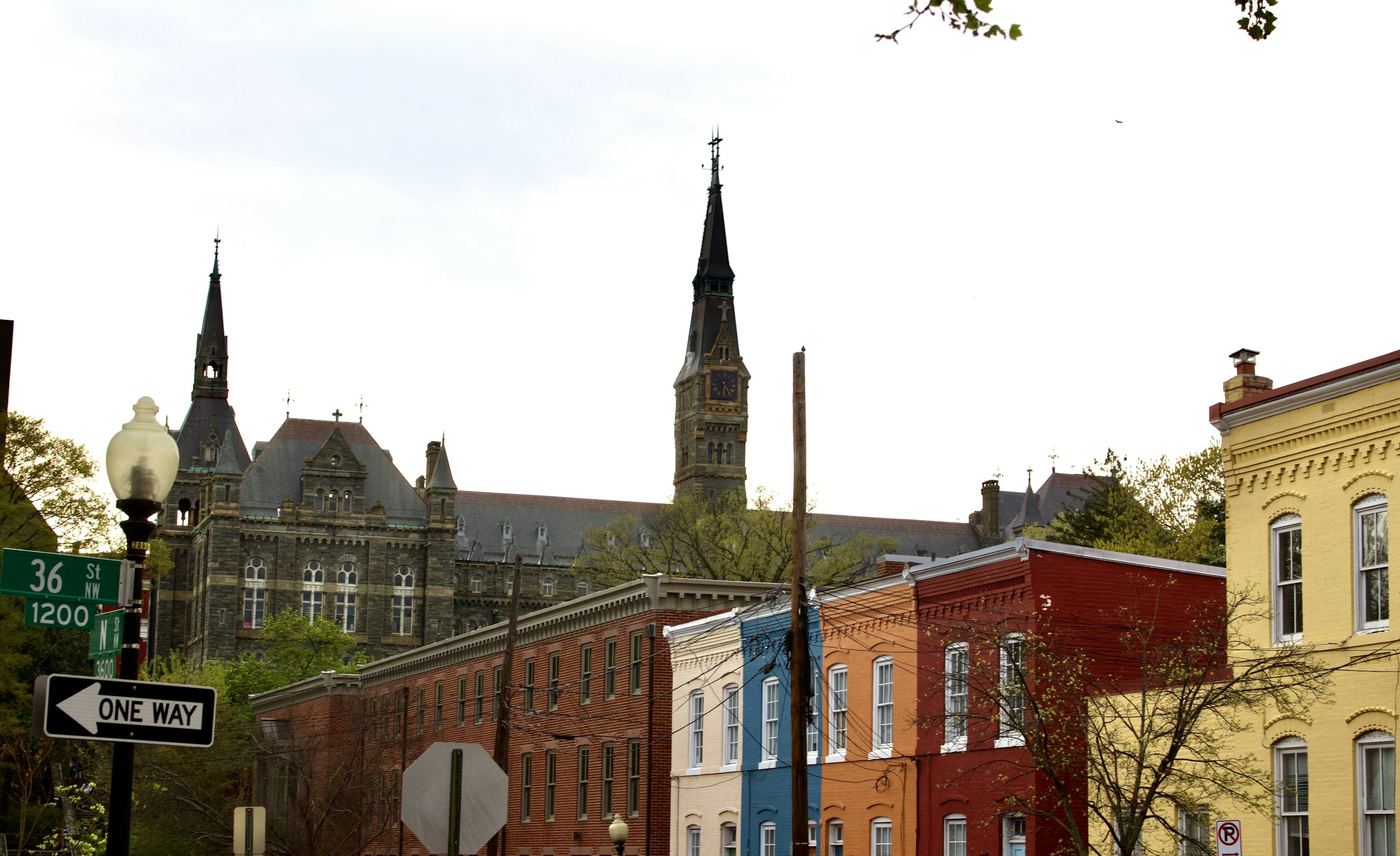
Showing Washington, DC.
Financing and preapproval
Speak with a lender before you tour. A prequalification or preapproval letter states how much a lender is willing to lend you, up to a certain amount and based on certain assumptions. Lenders use the two terms differently, and neither letter is a guaranteed loan offer.
Once you apply, the lender must deliver or mail a Loan Estimate by the third business day: the interest rate, the monthly payment and the closing costs, set out in the same federal form by every lender so that offers can be compared line by line.
A loan above the conforming loan limit is a jumbo loan. Fannie Mae and Freddie Mac do not buy jumbo loans, and they can cost more. With a cash purchase, the seller can ask for proof of funds with the offer. To see a price as a monthly payment, use the mortgage calculator.
- Conforming loan limit, one unit, 2026
- $1,249,125
- Two, three and four units, 2026
- $1,599,375, $1,933,200 and $2,402,625
- Loan Estimate
- Delivered or mailed by the third business day after your loan application
Buyer representation
Before an agent who belongs to a multiple listing service tours a home with you, in person or by live video, the two of you sign a written buyer agreement. This has been the rule since August 17, 2024. Asking an agent questions at an open house does not need one.
The agreement states the agent’s compensation in objective terms: a flat fee, a percentage or an hourly rate, never an open-ended amount. The agent cannot receive more than that amount from any source. Fees are not set by law and are negotiable. A seller can still offer to pay a buyer’s broker outside the MLS, and can offer concessions toward a buyer’s costs.
- When the agreement is signed
- Before touring, under the rule for MLS participants. DC law also requires a written Disclosure of Brokerage Relationship no later than when specific real estate help is first given.
- What it must contain
- A definite end date, 90 days if none is stated. Before the relationship begins, the agent discloses the broker’s compensation and whether it will be shared.
The search
Most homes for sale in DC, Maryland and Northern Virginia are listed on Bright MLS, the region’s multiple listing service. Some are marketed before they are active there, as Coming Soon listings, or privately within a brokerage’s own network as private or office exclusives. Those are covered under off-market opportunities.
The form of ownership decides what you review and how you finance. A condominium unit is real property inside an association, with its own documents and fees. A cooperative is a share in a corporation that owns the building, held with a proprietary lease: the co-op board usually reviews the buyer, and the loan is a share loan rather than a mortgage. A house in a homeowners association comes with the association’s rules and dues.
In a historic district, exterior changes are reviewed before a permit is issued. A buyer planning an addition, new windows or a new roof should know which review applies before making an offer.
- Historic district review
- The Historic Preservation Office reviews minor exterior work; the Historic Preservation Review Board hears larger work, such as additions, demolition and roof additions seen from the street. Interior work and painting are exempt.
- Georgetown
- Under the Old Georgetown Act, the Commission of Fine Arts reviews construction, alteration and demolition seen from a public street, including height, color and materials.
- A home with a tenant
- A single-family home, or a single rented condo or co-op unit, is exempt from the Tenant Opportunity to Purchase Act, except for a tenant who is 62 or older or disabled and whose lease was signed by March 31, 2018. The owner must still tell the tenant in writing within 3 calendar days of receiving a written offer.
The offer
Your agent writes the offer on the region’s standard sales contract, with addenda for each contingency and for the jurisdiction’s disclosures. When both parties have signed and the signed contract has been delivered, it is ratified, and the deadlines in it run from that date.
Price is one term of eight, and each can be negotiated:
- Price
- Deposit
- Contingencies
- Seller subsidy
- Settlement and occupancy dates
- Property condition
- Inclusions and exclusions
- Financial statement
Where several offers compete, an escalation clause raises your price by a set amount above a competing offer, up to a maximum you name. An appraisal gap provision commits you to pay a stated amount above the appraised value if the appraisal comes in below the price.
- The standard contract
- The GCAAR Sales Contract, with the DC Jurisdictional Disclosure and Addendum.

Contingencies and reviews
Between ratification and settlement, each contingency in the contract is worked through by its own deadline: the home inspection and any tests, the appraisal, the loan, and the review of the seller’s and the association’s documents.
A home inspection reports on the condition of the home for you. An appraisal estimates its value for the lender. They are separate, and the lender’s appraisal does not replace an inspection. The EPA and the Surgeon General recommend testing every home for radon. Some loans require a wood-destroying insect inspection.
For a home built before 1978, the seller gives you the federal lead-based paint disclosure and the EPA pamphlet before the contract, and you have 10 days to have the home tested for lead, unless the two of you agree a different period in writing or you waive it.
- Seller’s disclosure
- The seller delivers the disclosure statement on or before you sign the contract. If it arrives later, you may terminate by written notice within 5 days of receiving it, and your deposit is returned.
- Condominium documents
- The seller delivers the condominium documents and a resale certificate within 10 business days of the contract. You may cancel within 3 business days of receiving them.
- Lead-based paint
- Homes built before 1978: the federal disclosure, the EPA pamphlet, and 10 days to test.
Preparing for settlement
A title company or settlement attorney conducts settlement. It searches the title, prepares the documents, records the deed and pays off the seller’s loans. A seller cannot require you to buy title insurance from a particular company.
The lender’s title policy protects the lender. The owner’s policy protects you; it is optional and is bought once, at settlement.
You receive the Closing Disclosure at least three business days before settlement. Compare it with your Loan Estimate. A new three-day wait starts only if the APR becomes inaccurate, the loan product changes or a prepayment penalty is added.
Before you wire funds, call the settlement company at a number you already have and confirm the instructions. Never use a number or a link in an email: wiring instructions are a common target of fraud.
Shortly before settlement, the final walk-through confirms the home’s condition, that agreed repairs are done, and that the items included in the sale are still there.
- Choosing the settlement company
- Federal law bars a seller from requiring a particular title insurer.
- Closing Disclosure
- At least three business days before settlement
Settlement
At settlement you sign the note and the deed of trust, which secures the loan on the home; the seller signs the deed; the funds are disbursed; and the deed is recorded in your name. Recordation and transfer taxes are paid when the deed is recorded, and the contract says who pays which.
- Recordation tax
- 1.1% of the price under $400,000, and 1.45% of the whole price at $400,000 or more. By law buyer and seller are both liable; the contract says who pays.
- Transfer tax
- The same rates, owed by the seller.
- First-time buyers
- Recordation tax of 0.725% for a DC resident who has never owned a DC homestead, on a house or condo of $794,000 or less, with household income within the limit: $209,340 for one person, $298,980 for four (form ROD 11, from October 1, 2026). The whole benefit goes to the buyer.
- Cooperatives
- Recordation tax of 2.2% under $400,000 and 2.9% at $400,000 or more, and no transfer tax.
After settlement
Apply for the homestead benefit on your principal residence once the deed is recorded. It lowers or caps the property tax on the home you live in.
- Homestead
- The Homestead Deduction takes $91,950 off the assessed value for tax year 2026. Apply on form ASD-100, between October 1 and March 31 for the full year. The taxable assessment of a homestead property can rise by no more than 10% a year.
- Property tax per $100 of assessed value
- $0.85 for residential property. On a home of no more than two units, assessed value above $2.558 million is taxed at $1.00. The tax year runs from October 1.
Glossary
- Appraisal
- An estimate of the home’s value, made for the lender. It is not an inspection.
- Appraisal gap
- A provision in which the buyer agrees to pay a stated amount above the appraised value if the appraisal comes in below the price.
- Bright MLS
- The multiple listing service for DC, Maryland and Northern Virginia, where agents list homes for sale.
- Closing Disclosure
- The federal form with the final terms and costs of the loan, received at least three business days before settlement.
- Comparative market analysis
- An agent’s estimate of a home’s market value from recent comparable sales.
- Conforming loan limit
- The largest loan Fannie Mae and Freddie Mac will buy, set each year by the Federal Housing Finance Agency.
- Contingency
- A term of the contract that lets the buyer withdraw if a condition is not met, such as financing, the appraisal or the home inspection.
- Cooperative (co-op)
- Ownership of shares in a corporation that owns the building, with a proprietary lease on a unit.
- Deed
- The document that transfers ownership from the seller to the buyer, recorded at settlement.
- Deed of trust
- The document that secures the loan on the home, giving the lender a claim on it until the loan is repaid.
- Dual agency
- One brokerage representing both the buyer and the seller in the same sale.
- Earnest money deposit
- A good-faith deposit made with the offer, held in escrow and applied to the buyer’s costs at settlement.
- Escalation clause
- A term that raises the offer by a set amount above a competing offer, up to a stated maximum.
- Final walk-through
- The buyer’s visit shortly before settlement to confirm the home’s condition, the agreed repairs and the included items.
- Homestead benefit
- A property tax reduction or assessment cap for an owner who lives in the home: the Homestead Deduction in DC and the Homestead Tax Credit in Maryland.
- Jumbo loan
- A mortgage above the conforming loan limit.
- Loan Estimate
- The federal form a lender delivers or mails by the third business day after a loan application, with the rate, payment and closing costs.
- Owner’s title insurance
- An optional policy, bought once at settlement, that protects the buyer against covered defects in the title.
- Post-settlement occupancy
- An agreement for the seller to stay in the home for a period after settlement.
- Prequalification and preapproval
- Letters that state how much a lender is willing to lend, up to an amount and based on certain assumptions. Lenders use the terms differently, and neither is a guaranteed loan offer.
- Private exclusive
- A home marketed within one brokerage’s network before or instead of a listing on the MLS.
- Ratification
- The point at which both parties have signed and the signed contract has been delivered. The contract’s deadlines run from this date.
- Recordation tax
- A tax charged when the deed, and in some cases the deed of trust, is recorded.
- Resale certificate
- The association’s statement of fees, rules and finances for a condominium, co-op or HOA unit, with a review period for the buyer.
- Seller subsidy
- A credit from the seller toward the buyer’s closing costs, written into the contract.
- Settlement
- The meeting at which documents are signed, funds are disbursed and the deed is recorded. Called closing in much of the country.
- Settlement company
- The title company or attorney that conducts settlement. The buyer has the choice of company.
- Title search
- A review of public records to confirm the seller can convey the home and to find any liens.
- TOPA
- DC’s Tenant Opportunity to Purchase Act, which gives tenants rights when a rented home is sold.
- Transfer tax
- A tax on the transfer of the property, charged when the deed is recorded.
- Under contract
- The period from ratification to settlement.
- Wood-destroying insect inspection
- An inspection for termites and other insects that damage wood, required by some loans.
- Written buyer agreement
- The signed agreement between a buyer and an agent that sets out the agent’s services and compensation, required before touring.
